| Table of Contents |
This content is for informational purposes only. It does not constitute financial, legal, tax or regulatory advice. Each company should validate its payment implementation with its internal teams and external advisors.
Ask any finance committee about stablecoins for business payments, and you'll hear the same five objections before the meeting is over: too volatile, too risky, too crypto, an accounting headache, and the fear of getting locked into one provider for good.
Some of that is fair. Some of it is outdated. None of it deserves a one-line dismissal, and none of it deserves a one-line defense either.
This article goes through the five objections finance teams raise most often about stablecoins for business payments, in plain language: what is actually true, what no longer holds up, and what mitigates the risk that remains where it does. This is not about winning the argument. It is about knowing which objections deserve a real answer and which ones are just familiar fears wearing a technical costume.
The 5 objections finance teams raise about stablecoins for business payments
Before going deep on each one, here is the honest scorecard. Some objections hold up. Others do not survive contact with how these payments actually work in practice.
|
Objection |
Verdict |
|
1. “Too volatile” |
Mostly myth |
|
2. “Too risky” (issuer / reserves) |
Real, and worth checking |
|
3. “Too complicated” (accounting) |
Depends on how you use it |
|
4. “Too crypto” (perception) |
Mostly myth in practice |
|
5. “Too locked in” (one provider) |
Real, but avoidable |
Objection 1: “It’s too volatile”
A finance committee’s first objection to stablecoins usually starts with the word “crypto,” and crypto means Bitcoin-style price swings in most people’s minds. That comparison is exactly where the objection breaks down, and where it also earns a partial point.
The myth part: a well-collateralized, dollar-pegged stablecoin is not designed to move like Bitcoin. It is designed to track $1, and for the overwhelming majority of the time, it does, down to fractions of a cent.
The real part: “designed to hold its peg” is not the same as “cannot lose it.” Both leading dollar stablecoins have broken their peg under stress. USDC fell to about $0.87 in March 2023, after its issuer disclosed exposure to the collapse of Silicon Valley Bank, and recovered within days once depositors were made whole. USDT dropped to roughly $0.95 in May 2022, during the collapse of Terra’s UST, and also recovered within days. Neither event lasted, but both were real, and both had a specific, identifiable cause: reserve exposure and market panic, not the stablecoin model itself failing.
For a business running cross-border payments in Latin America, the more useful mitigation is not reserve quality alone, it is exposure time: how long a payment actually holds a stablecoin balance before it becomes local currency. In most stablecoin payment flows, the stablecoin is a bridge, not a destination. Dollars convert in, move across the border in minutes, and convert out to pesos, priced through USDC to MXN liquidity at the moment of settlement. When that conversion happens the same day a payment is initiated, a business is exposed to volatility for minutes, not for the days it would take a peg to break and recover.
The honest framing: this objection is mostly a myth for day-to-day use, and a real, if rare, tail risk that finance should still ask about, specifically, how quickly a provider converts in and out, and which stablecoin and issuer sit behind that conversion.
Objection 2: “It’s too risky”, what if the issuer or the reserves fail?
This is the objection with the most real substance, and it deserves to be treated that way instead of waved off.
Every stablecoin is only as strong as the entity issuing it and the assets backing it. That is not a crypto-specific problem, money market funds and bank deposits carry the same logic, but the maturity of that oversight still varies between issuers. USDC publishes monthly attestations of a reserve held almost entirely in cash and short-term US Treasuries. USDT reports on a quarterly basis, with a reserve mix that has historically included a smaller share of cash-equivalents alongside other assets. Neither disclosure practice is inherently wrong, but they are not equivalent, and a finance team should know the difference before choosing which stablecoin sits behind a payment flow.
What changed the picture in 2026 is regulation catching up to the question. The GENIUS Act in the US and MiCA in the EU now require permitted issuers to hold reserves 1:1 in high-quality liquid assets and publish regular attestations; the due diligence finance teams used to have to piece together on their own is now a licensing requirement in the largest corridors.
The realistic mitigation is not “avoid the risk,” because it cannot be avoided entirely. It is “choose the issuer and check the paperwork”, the same due diligence a treasury team already applies to a bank or a fund. A short list to start with: is the issuer licensed in the jurisdictions where you operate, are reserves held 1:1 and independently attested, and how often is that attestation actually published?
Objection 3: “It’s too complicated”, does this create an accounting headache?
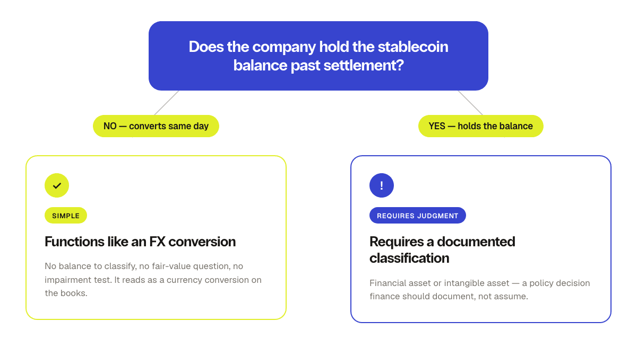
This objection deserves an honest “it depends,” because the answer turns on one decision a company makes early: does it hold a stablecoin balance, or does the stablecoin pass through?
Here is the part that surprises a lot of finance teams. When US accounting standards were updated in 2023 to let certain crypto assets be measured at fair value instead of the older cost-less-impairment model, that relief was written narrowly. The update, ASU 2023-08, excludes crypto assets that give the holder an enforceable claim on an underlying asset, which is exactly what a redeemable, fiat-backed stablecoin gives you. In practice, the fair-value relief that applied to bitcoin holdings does not automatically extend to stablecoins, so the classification question, financial asset or intangible asset, still requires judgment, and that judgment should be documented rather than assumed. International reporting under IFRS raises a similar question, without a fully settled answer either.
That is the real part of the objection. Here is the part that resolves it for most business payments use cases: none of that classification question matters if a company never holds a stablecoin balance at period-end. If dollars convert to a stablecoin and settle to local currency within the same payment flow (the pattern already common in mass payouts in Latin America and vendor payments) there is no balance to classify, no fair-value question and no impairment test to run. In the books, the transaction looks like an FX conversion, because functionally, that is what it is.
The mitigation, in other words, is architectural: keep stablecoins in motion rather than on the balance sheet, and the “crypto accounting” problem mostly disappears. Finance only needs a documented policy for the balances a company actively chooses to hold, which, for most business payments use cases, is close to zero.
Objection 4: “It’s too crypto”, the reputational objection
This is less a technical objection and more a gut reaction, and it is worth taking seriously precisely because gut reactions are what stall a committee vote.
Some of the discomfort is earned. Stablecoins share infrastructure with a part of the crypto industry that has generated real headlines: exchange collapses, and, more relevant to compliance teams, a documented rise in the use of stablecoins for sanctions evasion and illicit finance. Chainalysis’s 2026 Crypto Crime Report found that the value flowing to sanctioned entities rose 694% in 2025, and issuers now routinely freeze wallets tied to sanctioned actors once identified, a compliance response that barely existed a few years ago.
Here is what the data says about how businesses that actually adopt stablecoins for business payments behave, and it does not look like the crypto headlines. A January 2026 PYMNTS survey of 60 US middle-market CFOs found that among companies already using stablecoins, 88% use them to pay domestic suppliers, and 88% of the stablecoins they receive get converted to US dollars immediately. That is not speculative crypto behavior. That is a payment rail being used like a payment rail.
The mitigation is mostly about framing internally: separate the payments conversation from the digital-assets-as-investment conversation. A treasury policy that treats stablecoins as a settlement instrument, with the same compliance screening as any other cross-border payment, looks nothing like a crypto trading desk, and a provider that runs KYC, KYB and transaction monitoring on every flow answers the reputational objection with a paper trail, not a slogan.
Objection 5: “We’ll be locked into one provider”
This objection is real, but it is aimed at the wrong target. Stablecoins do not create vendor lock-in. A specific implementation choice does.
The pattern that does lock a company in is building around one issuer’s proprietary token or one closed rail, so switching later means rebuilding integrations, renegotiating terms and potentially re-onboarding counterparties. Some providers even encourage this by pitching companies on issuing their own branded stablecoin, which solves a different problem than the one most finance teams actually have, and deepens dependency rather than reducing it.
The pattern that avoids lock-in is choosing infrastructure that is issuer-agnostic and multi-rail from the start: a single API for cross-border payments in LATAM that can quote, convert and settle across more than one stablecoin and more than one local payment rail, so a business is never one issuer decision away from rebuilding its payment stack. In Mexico, for example, Bitso Business settles dollar-to-peso flows through a regulated IFPE with direct SPEI* access, so the local settlement leg runs on the country’s own interbank rail rather than a proprietary channel tied to one stablecoin. The same design principle applies to mass payouts in Latin America, where a marketplace or platform paying thousands of sellers or contractors needs the freedom to route each payout through whichever rail performs best in that corridor, not the rail that happens to match one issuer’s token.
The honest mitigation is a contract and architecture question, not a stablecoin question: ask any provider how you would move to a different rail if you needed to, and how much of that work you would inherit versus how much they would absorb.
The honest scorecard, one more time
Five objections, three real risks worth managing (issuer and reserve quality, the accounting choice a company makes, and provider architecture) and two that mostly dissolve once a payment flow is designed correctly (day-to-day volatility and the “crypto” label). None of that is a reason to rush a decision, and none of it is a reason to treat stablecoins for business payments as either a solved problem or a landmine. The real work is asking the specific questions above before scaling.
FAQs
Do companies need to hold a stablecoin balance to use stablecoins for business payments?
No. Most business payment flows convert dollars in and local currency out within the same transaction, so the company never carries a stablecoin balance on its books.
Which of the five objections has the most real substance today?
Issuer and reserve risk. Reserve composition and attestation frequency genuinely differ between issuers, and that difference is worth checking before choosing a rail, even though 2026 regulation raised the baseline.
Are stablecoins regulated the same way in every market?
No. The US, the EU, Mexico, and other countries in LatAm, each apply a different framework, with different licensing and reserve requirements.
How many companies already use stablecoins for business payments?
Adoption is still early by most measures. A January 2026 PYMNTS survey found that only 13% of US middle-market firms currently use stablecoins, while 58% of CFOs have not yet considered it, even though regulatory clarity has improved.
Does using stablecoins expose a company’s treasury to crypto market swings?
Not in the way most committees imagine. A dollar-pegged stablecoin is designed to track $1, and the businesses that use one to pay suppliers or run payouts typically hold it for minutes, not days, which limits exposure to the rare de-peg events described above.
*NVIO México enables direct access to SPEI and delivers payment services fully compliant with Mexican regulation. NVIO Pagos México, S.A.P.I. de C.V., IFPE (“NVIO México”) is authorised and regulated by the Mexican National Banking and Securities Commission (CNBV). Learn more at nvio.mx/terms.