by Bitso on Oct 05, 2026
| Table of Contents |
This content is for informational purposes only. It does not constitute financial, legal, tax or regulatory advice. Each company should validate its payment implementation with its internal teams and external advisors.
A single stablecoin payment looks simple from the outside. Money leaves one account and lands in another, often in minutes. In practice, a business payment is rarely just one movement. It usually involves a conversion, a transfer, another conversion, and a delivery into a bank account, a wallet, or a local rail. Each of those steps has to match against something else: an invoice, a purchase order, an approved vendor, an expected amount. As stablecoin volume grows, from cross-border payments in Latin America to recurring mass payouts in Latin America across marketplaces and payroll providers, that matching work is what Finance teams actually struggle to keep up with. Not the settlement. The reconciliation.
Artificial intelligence is starting to change what “automated reconciliation” means in practice, and the change is narrower than the label suggests. AI takes on the part of the job that rule-based automation was never built to scale: matching payments that do not arrive in a tidy, predictable shape, without touching the approval workflow or the ERP underneath.
Here is what that looks like today, and where it actually helps.
Why reconciliation gets harder before it gets easier
A stablecoin payment for business use is rarely a single leg. Money typically converts into a stablecoin, moves across a network, and converts back into local currency before it reaches a supplier, an employee, or a marketplace seller. Each leg produces its own data: a rate, a timestamp, a transaction ID, a reference. When volume is low, a person can compare all of that by hand without much friction.
The friction shows up with scale. A company running mass payouts in Latin America to hundreds of sellers a week, or opening a second or third cross-border corridor, starts to see references formatted differently by every counterparty and invoices numbered inconsistently between ERPs. That is not fraud, just noise that grows faster than the team reviewing it can keep up with.
What rule-based automation already solved, and where it stops
Most reconciliation tools already automate a version of this: they match a unique reference number to an invoice, confirm status through a webhook, and flag anything that does not line up exactly. That approach works well when every counterparty follows the same format.
It stops working as cleanly the moment a marketplace changes how it numbers invoices, an ERP truncates a field, or a payout crosses into a corridor with a different local ID convention. Optimus, a reconciliation software provider, reports exactly this ceiling: exact-match, reference-based tools treat every formatting difference as an exception, even when a person would recognize the match immediately. The result is a queue full of items that never needed a decision, sitting next to the few that do.
What an AI layer actually does with a stablecoin transaction
Stablecoin infrastructure providers are already building this directly into the payment stack rather than around it (Fireblocks, 2026). In practical terms, an AI reconciliation layer changes three things about that queue.
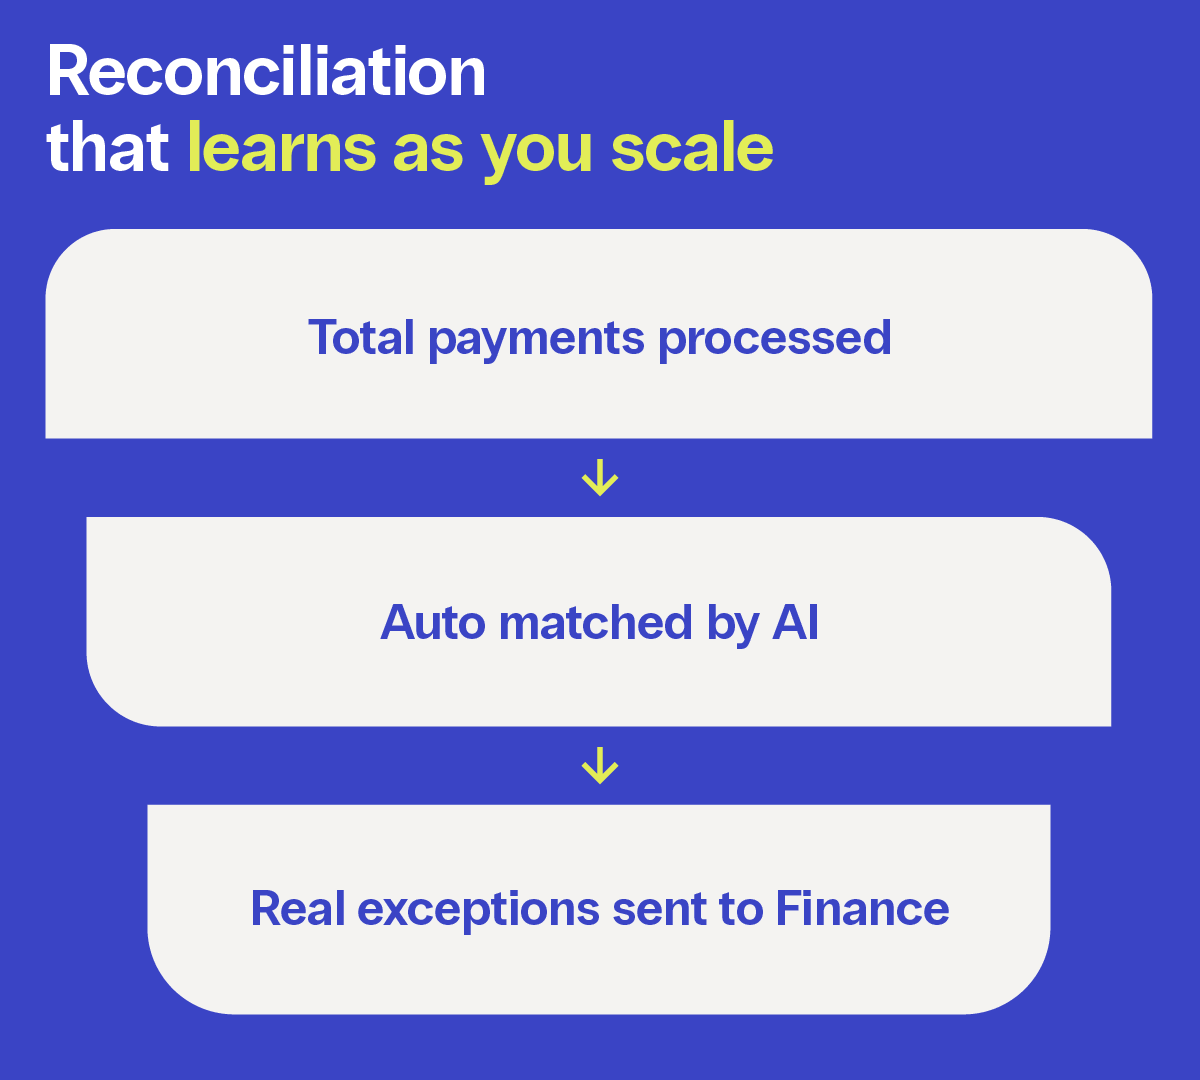
First, it reads transaction data across formats without requiring an identical structure from every source, a method usually called fuzzy matching: it recognizes that an invoice number, a payment reference, and a memo field describe the same transaction even when none of them are written the same way. Second, it learns how a specific counterparty, ERP, or marketplace tends to format amounts, dates, and fees, and adjusts to that pattern instead of applying one rigid rule to everyone, which is the part that improves with volume rather than breaking under it.
Third, it separates a real exception, a wrong beneficiary, a duplicate payment, a mismatched amount, from a formatting difference that never needed a person to look at it. Independent analyses of AI-based reconciliation tools in 2026 report this distinction cutting false positive exception rates from roughly 10% to under 1% in production use, a sign of how far reconciliation tooling has moved across the industry this year.
The same logic applies to the currency conversion leg. For a corridor like USDC to MXN liquidity, a settled amount will legitimately differ from an invoiced amount by the spread applied at the moment of conversion. A model trained on a provider’s own rate history can tell a normal spread apart from a variance worth flagging, instead of treating both the same way.
Where this matters most today
Mass payouts in Latin America are the clearest case. A marketplace or gig platform sending thousands of payments in a single batch does not need every payment reviewed individually; it needs the handful that are actually wrong surfaced quickly. Grouping exceptions instead of listing them one by one is what turns a review of thousands of lines into a review of a few dozen. For a deeper look at how this fits into the wider payment ecosystem, see Bitso Business’s guide to stablecoins for business payments in LatAm.
The same logic extends to cross-border payments in Latin America more broadly. An API for cross-border payments in LATAM can deliver clean, structured transaction data. What a Finance team does with that data as volume grows still depends on whether the matching layer underneath can adapt to new counterparties and formats without a new manual rule for each one.
The data behind the match
None of this works without structured data traveling with the payment in the first place. In Mexico, the local leg of a cross-border payment typically settles through SPEI, the real time interbank system Banco de México has operated since 2004. Since 2017, Banco de México’s Circular 14/2017 has set out the technical and operational rules for SPEI, including what data, account identifiers, payment concepts, and participant information, must accompany every transfer.
That data requirement is not a footnote for Compliance teams alone: it directly feeds the matching engine, AI-based or rule-based, that reconciles the transaction. Bitso Business delivers that local peso leg through SPEI*, so the stablecoin settlement and the local payout run inside the same regulated flow rather than around it. When the data arriving with a payment is incomplete, even the most capable model has less to work with, and more exceptions end up in a person’s queue regardless of how the system was built.
Rule-based matching vs. AI-assisted matching
|
Task |
Rule-based matching |
AI-assisted matching |
|
Matching logic |
Exact match on one reference field |
Recognizes the same transaction across different formats |
|
What gets flagged |
Every mismatch, regardless of cause |
Only the mismatches that need a human decision |
|
Improves with volume |
No, same rules until someone updates them |
Yes, adjusts as it processes more transactions |
|
Currency conversion legs |
Flags any variance from the invoiced amount |
Distinguishes normal spread from a real error |
|
Best fit today |
Stable volume, one format, one corridor |
Growing volume, multiple counterparties and corridors |
If your team is also confirming the regulatory side of this shift, Bitso Business’s regulatory map for 2026 pairs well with this piece.
FAQs
Does AI reconciliation replace our ERP or approval workflow?
No. Approvals, cost centers, and the general ledger stay exactly where they are today. An AI reconciliation layer sits on top, matching the stablecoin transaction data, amount, reference, counterparty, status, to the invoice or purchase order your team already approved. What changes is how much of that matching a person has to do by hand.
Is this only useful for companies moving very large volumes?
Volume is what makes the difference visible, not what makes it necessary. A handful of monthly payments can be reconciled by hand without friction. The moment a business scales into recurring mass payouts in Latin America, or opens a second cross-border corridor, the matching work grows faster than headcount usually does, and that is the point where an AI layer starts to pay for itself.
How does this handle the currency conversion step, like usdc to mxn liquidity?
The conversion leg is where a lot of false exceptions come from, because the settled amount will legitimately differ from the invoiced amount by the spread applied at the moment of conversion. A model trained on a provider’s own rate history can recognize a normal spread and only flag a variance that falls outside it.
*NVIO México enables direct access to SPEI and delivers payment services fully compliant with Mexican regulation. NVIO Pagos México, S.A.P.I. de C.V., IFPE (“NVIO México”) is authorised and regulated by the Mexican National Banking and Securities Commission (CNBV). Learn more at nvio.mx/terms.